Schedule a demo
Menu
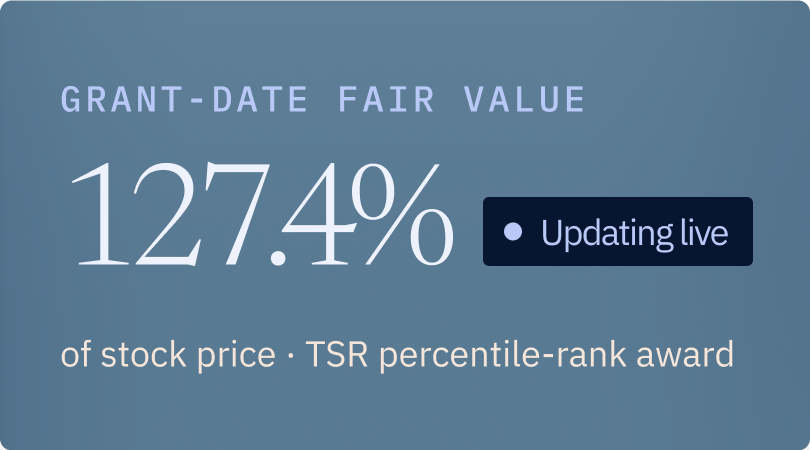
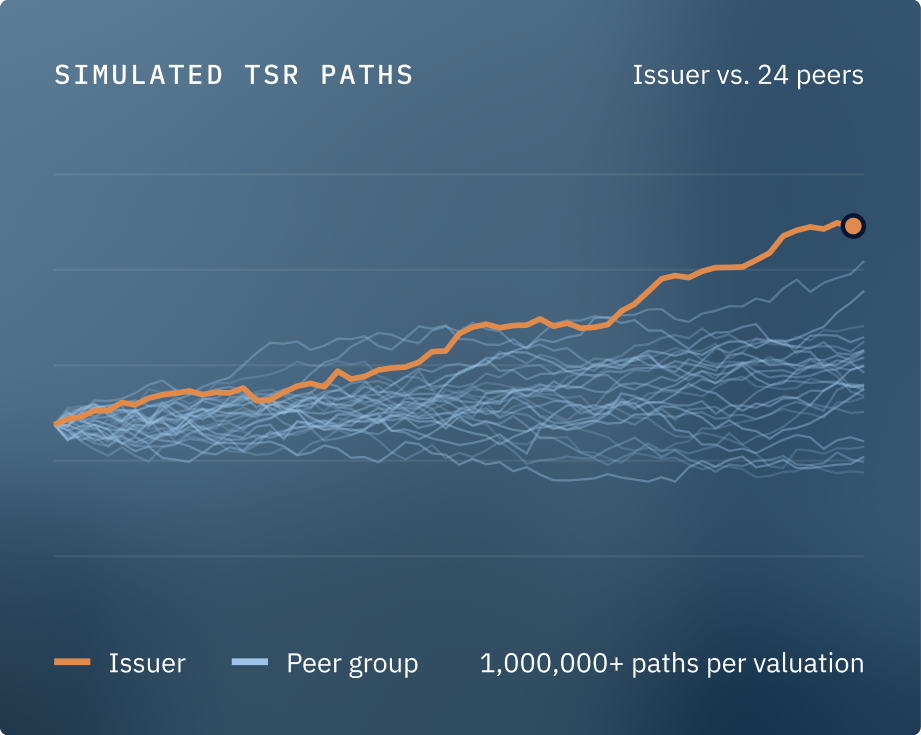
Monte Carlo design and valuation of relative TSR awards, PvP CAP table mark-to-market valuations, modification valuations and stock options with intensity-based expected term. Plus ESPP resets, warrants, convertible debt and other derivative securities. Valuing equity compensation for two decades. Hundreds of clients, from microcap to Fortune 100. Tens of thousands of successfully audited valuations. Level contact on every engagement, directly with the valuation specialist. FAS Solutions, since 2005, has been trusted by Executive Compensation and Finance Teams at America’s most well-known Fortune 50 companies and hundreds of large cap to small cap companies. Across banking, investment banking, insurance, media, technology, pharmaceuticals, medical, consumer products, industrials, energy, airlines, hotels and REITs. TSR Design Fulcrum offers clients Monte Carlo models that are customizable to your specific needs. Design your relative TSR award and see the fair values update in real time! Peer group, metric, payout levels, caps and grant timing. Volatility, correlation, risk-free rate, dividends and realized performance. The Monte Carlo fair value updates as you change any input. Custom Monte Carlo pre-grant valuations and design with TSR Design Fulcrum, grant-date valuations, mark-to-market PvP CAP valuations and modification valuations. Intensity-based Monte Carlo expected term, estimated econometrically from your own exercise and termination data, or from our cross-company knowledge base and datasets. Auditable ASC 718 valuations, PvP CAP tables and forecasts, delivered per our clients’ timing needs. See what each design choice costs before you vote, with TSR Design Fulcrum. Bring Ph.D.-level Monte Carlo modeling to support your advisory to the Board. We work behind the scenes. Independent, defensible quantitative analysis across all markets, from equity to prediction. “The compensation committee should see the cost of each choice before it decides.”The principle behind TSR Design Fulcrum Independent Monte Carlo valuation of derivative and structured securities to inform investment decisions. Defensible quantitative analysis of equity awards and derivatives for disputes and expert reports. Quantitative tools to find arbitrage and gain an advantage across prediction markets. Peer group, metric, payout shape, structure and timing, and what each does to fair value. How an intra-period grant impacts the fair value of a relative TSR award. The econometric method behind the expected term. How grant-date fair value supports the accounting cost of relative TSR awards. How exercise behavior and expected term inform stock option valuations. Tell us about your awards, contemplated or granted. Let’s discuss how we can help with design, valuation and tracking. What happens next
The Monte Carloexperts for ASC 718and beyond

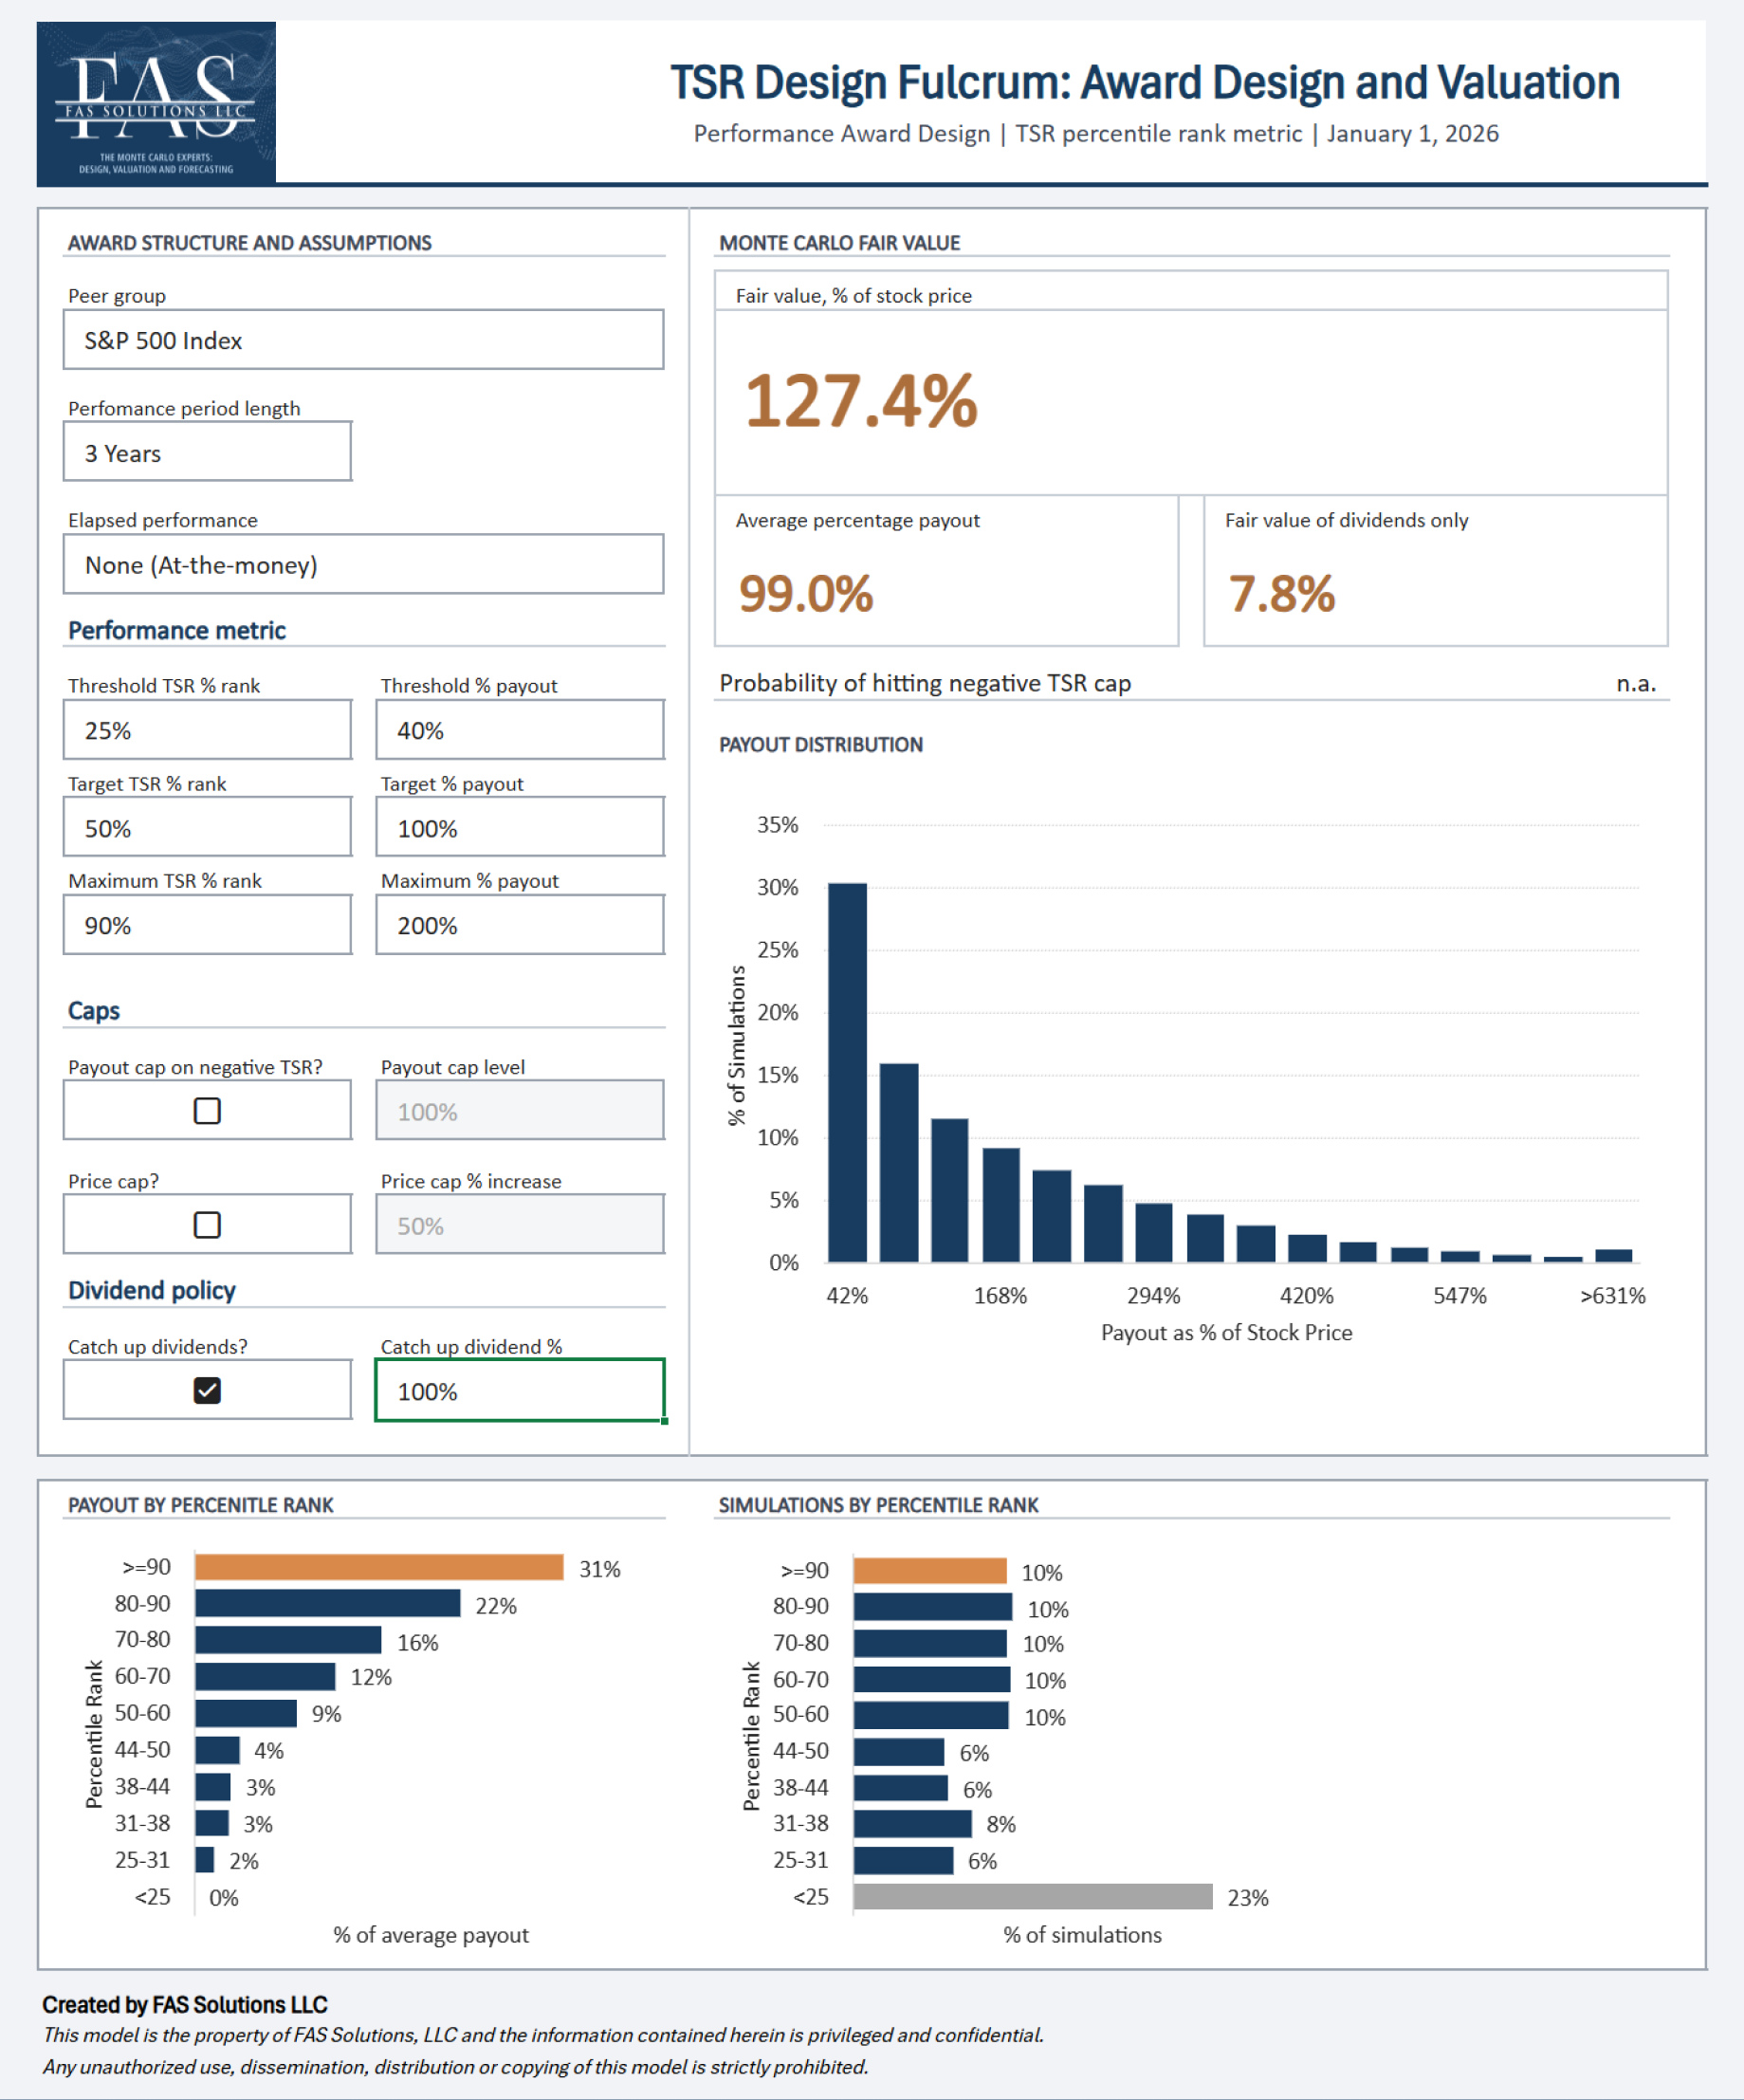
See the cost of every design choice before the committee decides.
Choose the structure
Choose the assumptions
See the fair value
Test a wide variety of rTSR structures
Quantitative depth across the
life of every award
Relative TSR awards
Stock options and expected term, ESPP, warrants, convertibles
Supporting important decisions for your next award
Finance and accounting teams
Compensation committees and executives
Executive compensation consultants
Investors and litigation teams
Equity Compensation and Beyond
Investors
Litigation support
Prediction markets
Explore our
design and valuation expertise
Relative TSR award design: the most impactful decisions
Granting after the performance period start date
Intensity-based expected term: how it works
ASC 718 grant-date valuation
Monte Carlo vs. Black-Scholes
Talk to a valuation expert
Request a consultation or demo